[
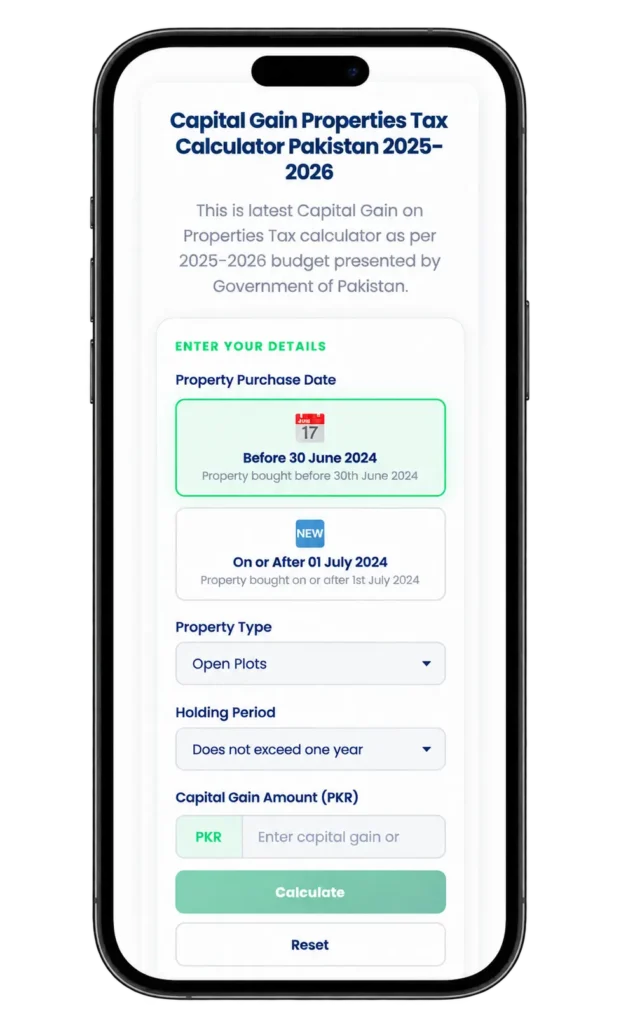
Capital Gain Properties Tax Calculator Pakistan 2025-2026
This is latest Capital Gain on Properties Tax calculator as per 2025-2026 budget presented by Government of Pakistan.
Capital Gain Properties Tax Calculator
Enter Your Details
Your Capital Gain Properties Tax Results
Based on FBR capital gain on properties tax rates for 2025-2026
Gain Tax on Properties Tax Calculator Pakistan 2026-2027
The Gain Tax on Properties Tax Calculator helps you estimate capital gains tax when you sell immovable property in Pakistan.
Property capital gains tax is charged under Section 37 of the Income Tax Ordinance, 2001. The calculation depends heavily on when you acquired the property.
Properties acquired on or before 30 June 2024 still use the older holding-period system. Properties acquired on or after 1 July 2024 use a different system based mainly on your Active Taxpayers’ List status and legal status.
This distinction is important. A plot bought in 2022 and a plot bought in 2025 can produce very different tax results even when both generate the same capital gain.
How to Use the Property Gain Tax Calculator
Start by selecting when the property was acquired.
For property acquired on or before 30 June 2024, enter:
For property acquired on or after 1 July 2024, enter:
The calculator should use the acquisition date to choose the correct legal framework automatically.
Enter the capital gain, not the total sale price.
If a property costs Rs 6 million and is sold for Rs 9 million, the simplified capital gain is Rs 3 million, not Rs 9 million.
What Is Capital Gain Tax on Property in Pakistan?
Capital gain is generally the profit arising when an asset is disposed of for more than its tax cost.
Section 37 uses the basic formula:
Capital Gain = Consideration Received – Cost of Asset
The current Income Tax Ordinance specifically applies Section 37(1A) to gains from immovable property situated in Pakistan.
Residential plots, commercial plots, houses, buildings and flats can therefore fall within the property capital gains framework.
The actual calculation can be more detailed than simply subtracting the original purchase price. Qualifying incidental expenses and improvement costs can also form part of the asset’s tax cost.
How Is Property Capital Gain Calculated?
A simplified calculation looks like this:
Sale consideration: Rs 12,000,000
Tax cost of property: Rs 8,000,000
Capital gain: Rs 4,000,000
You then apply the appropriate tax rate to the Rs 4 million gain.
The applicable rate depends first on whether the property was acquired on or before 30 June 2024 or on or after 1 July 2024.
For older properties, property type and holding period matter.
For newer properties, ATL and taxpayer status are more important.
Property Acquired on or Before 30 June 2024
The older regime still applies to properties acquired on or before 30 June 2024.
The current FBR schedule provides separate holding-period rates for open plots, constructed property and flats.
Holding period | Open plot | Constructed property | Flat |
|---|---|---|---|
Up to 1 year | 15% | 15% | 15% |
More than 1 year up to 2 years | 12.5% | 10% | 7.5% |
More than 2 years up to 3 years | 10% | 7.5% | 0% |
More than 3 years up to 4 years | 7.5% | 5% | 0% |
More than 4 years up to 5 years | 5% | 0% | 0% |
More than 5 years up to 6 years | 2.5% | 0% | 0% |
More than 6 years | 0% | 0% | 0% |
Property Acquired on or After 1 July 2024
The rules changed significantly from 1 July 2024.
For properties acquired on or after that date, the old declining holding-period rates no longer determine the tax.
If the seller appears on the Active Taxpayers’ List on the date of disposal, the rate is 15% of the capital gain.
The 15% rule applies irrespective of whether the property is an open plot, constructed property or flat.
This means holding a property purchased in 2025 for six years does not automatically reduce the rate to zero under the old system.
ATL vs Non-ATL Property Capital Gain Tax
ATL status matters greatly for property acquired from 1 July 2024 onward.
ATL seller
If you appear on the ATL on the date of disposal:
CGT = Capital Gain × 15%
Example:
Capital gain = Rs 5,000,000
Tax:
Rs 5,000,000 × 15% = Rs 750,000
Estimated capital gain tax:
Rs 750,000
Non-ATL individual or AOP
For a person not appearing on the ATL, the current property schedule refers to the normal Division I rates for individuals and AOPs.
However, it adds an important protection for the government:
The tax cannot be less than 15% of the capital gain.
Therefore, the correct calculator logic is:
Step 1: Calculate tax using the current Division I rate.
Step 2: Calculate 15% of the capital gain.
Step 3: Use the higher amount.
This is more accurate than creating a separate unofficial property slab table.
Example: Rs 1 million gain
Normal Division I tax on Rs 1 million:
15% of the amount above Rs 600,000:
Rs 400,000 × 15% = Rs 60,000
Minimum property CGT:
Rs 1,000,000 × 15% = Rs 150,000
The higher amount is:
Rs 150,000
Estimated CGT = Rs 150,000
Example: Rs 3 million gain
Normal Division I calculation:
Rs 170,000 + 30% of amount above Rs 1.6 million
Excess:
Rs 3,000,000 – Rs 1,600,000 = Rs 1,400,000
Tax:
Rs 170,000 + Rs 420,000 = Rs 590,000
Minimum 15% calculation:
Rs 3,000,000 × 15% = Rs 450,000
The normal calculation is higher.
Estimated CGT:
Rs 590,000
Current Company Rates for Property Gains
Where the post-July-2024 seller is not on the ATL and is a company, Division VIII refers to the current Division II company rates.
For Tax Year 2027, those rates are:
Company type | |
|---|---|
Small company | 20% |
Other company | 29% |
Banking company | 42% |
The 42% banking-company rate is important because older calculators may still show 39%. The current Income Tax Ordinance lists 44% for Tax Year 2025, 43% for Tax Year 2026 and 42% for Tax Year 2027 onward.
A business should not select “small company” simply because its property transaction is small. “Small company” is a defined tax status.
Property Capital Gain Tax Examples
Example 1: Old Open Plot
A plot was acquired in 2022.
Capital gain on sale:
Rs 4,000,000
Holding period:
More than 3 years but not more than 4 years.
Applicable open-plot rate:
7.5%
Tax:
Rs 4,000,000 × 7.5% = Rs 300,000
Estimated CGT:
Rs 300,000
Example 2: Old Flat
A flat was acquired before July 2024 and held for more than two years.
Capital gain:
Rs 3,000,000
Applicable rate:
0%
Estimated CGT:
Rs 0
The zero rate comes from the legacy holding-period schedule.
Example 3: New Property, ATL Seller
A property was purchased in September 2024.
Capital gain on sale:
Rs 6,000,000
Seller appears on ATL on disposal date.
Rate:
15%
Tax:
Rs 6,000,000 × 15% = Rs 900,000
Estimated CGT:
Rs 900,000
Example 4: New Property, Non-ATL Small Company
Capital gain:
Rs 6,000,000
Company type:
Qualifying small company
Current Division II rate:
20%
Tax:
Rs 6,000,000 × 20% = Rs 1,200,000
Estimated CGT:
Rs 1,200,000