Freelancer Tax Calculator Pakistan 2026-2027
This is latest freelancer tax calculator as per 2026-2027 budget presented by government of Pakistan.
Freelancer Tax Calculator Pakistan
Enter Your Details
Your Freelancer Tax Results
Based on PSEB registration rates for 2026-2027
Monthly Breakdown
Yearly Breakdown
Freelancer Tax Calculator Pakistan 2026-2027
The Freelancer Tax Calculator Pakistan helps you estimate tax on freelance income earned from foreign clients.
Pakistan has a special tax regime for qualifying exports of services. For Tax Year 2027, PSEB-registered exporters of qualifying computer software, IT services and IT-enabled services can use a 0.25% tax rate on export proceeds. Other qualifying exports of services under Section 154A generally use a 1% rate.
These rates are much lower than normal business-income tax rates. However, they do not automatically apply to every freelancer or every payment received from abroad.
Your type of service, PSEB registration and source of income matter
This calculator gives an estimate based on the information you enter. Your actual FBR treatment can depend on the nature of your services and whether you meet the conditions of Section 154A.
How to Use the Freelancer Tax Calculator
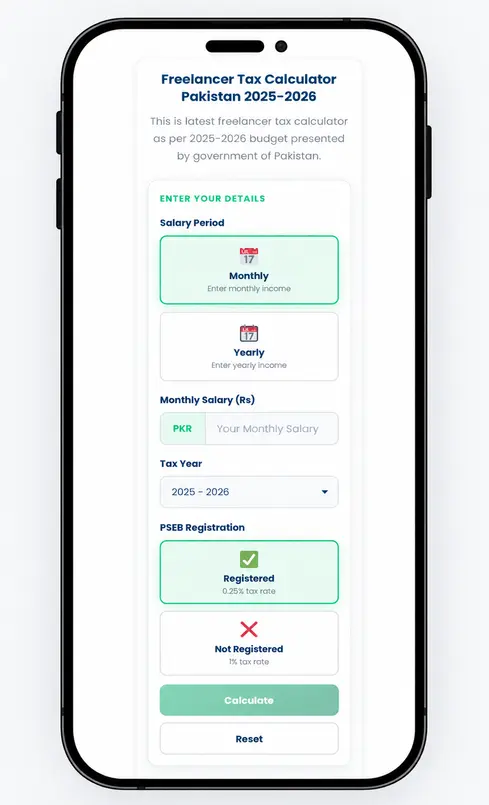
If your PSEB registration is valid and your income qualifies as an export of computer software, IT services or IT-enabled services, the calculator applies the 0.25% rate.
Otherwise, qualifying export services under Section 154A generally use the 1% rate.
Do not enter ordinary salary income into this calculator.
Income from Pakistani clients also needs separate treatment because it normally falls under the regular business-income rules.
Freelancer Tax Rates in Pakistan 2026-27
The two main Section 154A rates relevant to freelancers are:
Type of export income | Tax rate |
|---|---|
Computer software, IT or IT-enabled services by a PSEB-registered exporter | 0.25% |
Other qualifying cases under Section 154A | 1% |
Finance Act 2026 extended the reduced 0.25% rate through Tax Year 2029.
The 0.25% rate should therefore not be described as a temporary benefit ending in June 2026.
It continues for qualifying taxpayers under the current law.
Who Qualifies for the 0.25% PSEB Tax Rate?
The 0.25% rate is not a general tax rate for every person who calls themselves a freelancer.
Section 154A and the First Schedule apply the reduced rate to export proceeds from computer software, IT services or IT-enabled services where the exporter is registered with and duly certified by the Pakistan Software Export Board.
PSEB itself confirms that registered freelancers can access the 0.25% tax rate on eligible IT and IT-enabled service export proceeds.
Examples of IT and IT-enabled work can include activities such as software development, web development, web design, cloud computing, data entry, graphic design and certain other qualifying technology-enabled services.
However, receiving money from a foreign client does not automatically turn every service into PSEB-qualified IT or IT-enabled service income.
The nature of the service still matters.
How Is Freelancer Tax Calculated?
For a simple Section 154A estimate, the formula is:
Freelancer Tax = Qualifying Export Proceeds × Applicable Tax Rate
Suppose qualifying export proceeds are Rs 1,000,000.
If you qualify for the PSEB rate:
Rs 1,000,000 × 0.25% = Rs 2,500
Estimated tax:
Rs 2,500
If the 1% Section 154A rate applies:
Rs 1,000,000 × 1% = Rs 10,000
Estimated tax:
Rs 10,000
This shows why PSEB registration can make a large difference for freelancers whose services qualify for the reduced rate.
One wording point is important.
Section 154A refers to tax being deducted when foreign-exchange proceeds are realized by an authorized dealer. Therefore, the safest amount to use for tax reconciliation is the export proceeds shown in your banking or remittance records rather than simply assuming that every amount on a client invoice is the statutory tax base.
Freelancer Tax Calculation Examples
Example 1: PSEB-Registered Freelancer
Suppose a software developer earns qualifying export proceeds of:
Rs 500,000 per month
Annual export proceeds:
Rs 500,000 × 12 = Rs 6,000,000
PSEB rate:
0.25%
Annual tax:
Rs 6,000,000 × 0.25% = Rs 15,000
Estimated annual tax:
Rs 15,000
Average monthly tax:
Rs 1,250
Example 2: Freelancer Using the 1% Rate
Suppose another freelancer has qualifying Section 154A export proceeds of:
Rs 6,000,000 per year
Applicable rate:
1%
Calculation:
Rs 6,000,000 × 1% = Rs 60,000
Estimated annual tax:
Rs 60,000
Compared with Rs 15,000 at the PSEB 0.25% rate, the difference is Rs 45,000.
Example 3: Higher Export Income
Annual qualifying IT export proceeds:
Rs 12,000,000
At 0.25%:
Rs 12,000,000 × 0.25% = Rs 30,000
At 1%:
Rs 12,000,000 × 1% = Rs 120,000
These examples show the tax on the export proceeds only. They do not include unrelated income or another tax regime that may apply to the taxpayer.
Is the 0.25% or 1% Freelancer Tax Final Tax?
It can be final tax, but there are conditions.
Section 154A states that tax deducted under the section is final tax on the relevant income when the required conditions are met.
These conditions include filing the income tax return and filing withholding statements when they are required. Sales tax returns must also be filed where required, although the statute provides an exception to that particular condition for exporters falling under Section 154A(1)(a), which covers the specified PSEB-registered software, IT and IT-enabled service exports.
The taxpayer must also not claim a foreign tax credit against that income.
A taxpayer who does not fulfil the conditions, or who chooses not to use final taxation, can fall outside that final-tax treatment.
This distinction is important.
A bank deduction of 0.25% or 1% does not mean you can simply ignore your annual FBR return.
Foreign Client Income vs Local Client Income
A freelancer can have two very different types of income:
Foreign export income and Pakistani-client income.
They should not automatically be taxed the same way.
Qualifying export-of-services income can fall under Section 154A.
Income from services provided to Pakistani clients normally falls under ordinary business-income rules.
For local business income, allowable business expenses can reduce taxable income when they satisfy the Income Tax Ordinance. Section 20 generally allows expenditure incurred wholly and exclusively for the purposes of the business, subject to the other provisions of the law.
For example, a freelancer may have:
The foreign export portion and local business portion should not simply be combined and multiplied by 0.25%.
The local portion needs a separate business-income calculation.
Tax Rates for Freelancers Earning From Pakistani Clients
Local freelance income is generally business income rather than salary merely because you receive it every month.
For a non-salaried individual, the current basic tax schedule is:
Annual taxable income | Tax |
|---|---|
Up to Rs 600,000 | 0% |
Rs 600,001 to Rs 1,200,000 | 15% of amount above Rs 600,000 |
Rs 1,200,001 to Rs 1,600,000 | Rs 90,000 + 20% above Rs 1,200,000 |
Rs 1,600,001 to Rs 3,200,000 | Rs 170,000 + 30% above Rs 1,600,000 |
Rs 3,200,001 to Rs 5,600,000 | Rs 650,000 + 40% above Rs 3,200,000 |
Above Rs 5,600,000 | Rs 1,610,000 + 45% above Rs 5,600,000 |
These are business and non-salaried rates, not the separate salary schedule. The 2026 Finance Act changed salaried rates but did not replace this non-salaried schedule.
If you earn substantial income from Pakistani clients, your dedicated business or AOP tax calculator is the better tool for that part of your income.
PSEB Registration Requirements
PSEB currently lists the following main documents for freelancer registration:
PSEB states that a freelancer uses a personal NTN and personal bank account. A business owner operating with a business NTN does not use the same freelancer membership category.