Pakistan Income Tax Calculator 2026-2027
Professional salary tax estimates for salaried persons in Pakistan. Select a tax year (2026-2027 through 2013-2014), enter taxable income, and get instant annual & monthly breakdowns with slab analysis and year-over-year comparison.
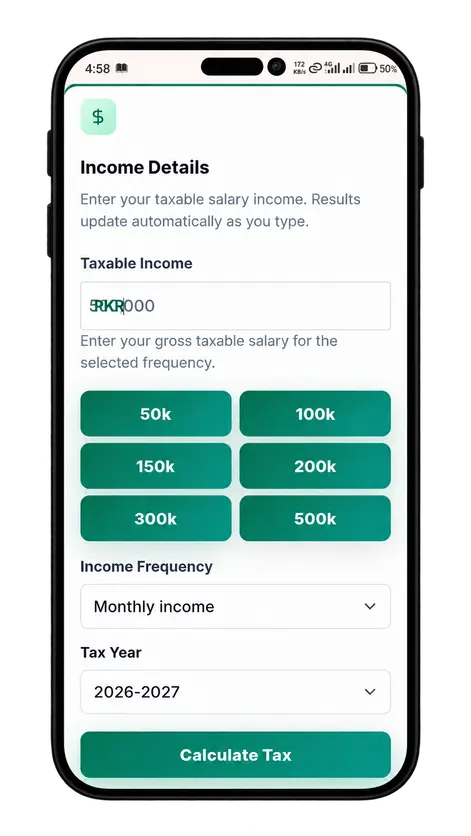
Income Details
Enter your taxable salary income. Results update automatically as you type.
Enter your gross taxable salary for the selected frequency.
Enter to calculate instantly · Auto-updates as you type
For salaried persons in Pakistan. Estimates based on official FBR salary tax slabs.
Ready to Calculate Your Tax
Enter your taxable salary on the left, pick a tax year, and see your complete breakdown — tax payable, take-home salary, slab details, and year comparison.
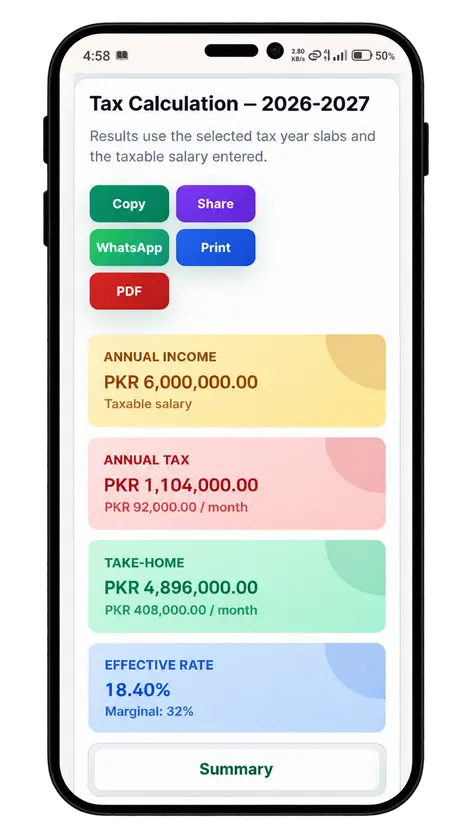
Tax Calculation — 2026-2027
Results use the selected tax year slabs and the taxable salary entered.
Yearly Results
Annual viewAnnual taxable income
-- PKR
Annual tax payable
-- PKR
Annual salary after tax
-- PKR
Monthly Results
Salary viewMonthly tax payable
-- PKR
Monthly salary after tax
-- PKR
Effective tax rate
--%
Not calculatedMonthly Payslip View
PayslipGross monthly salary
-- PKR
Monthly tax deduction
-- PKR
Net monthly salary
-- PKR
Employer Deduction View
WithholdingEstimated monthly withholding tax
-- PKR
Estimated annual withholding tax
-- PKR
This is an estimate for salary planning and payslip checking.
Tax Deduction Timeline
Estimated tax deductions across daily, weekly, and longer salary periods.
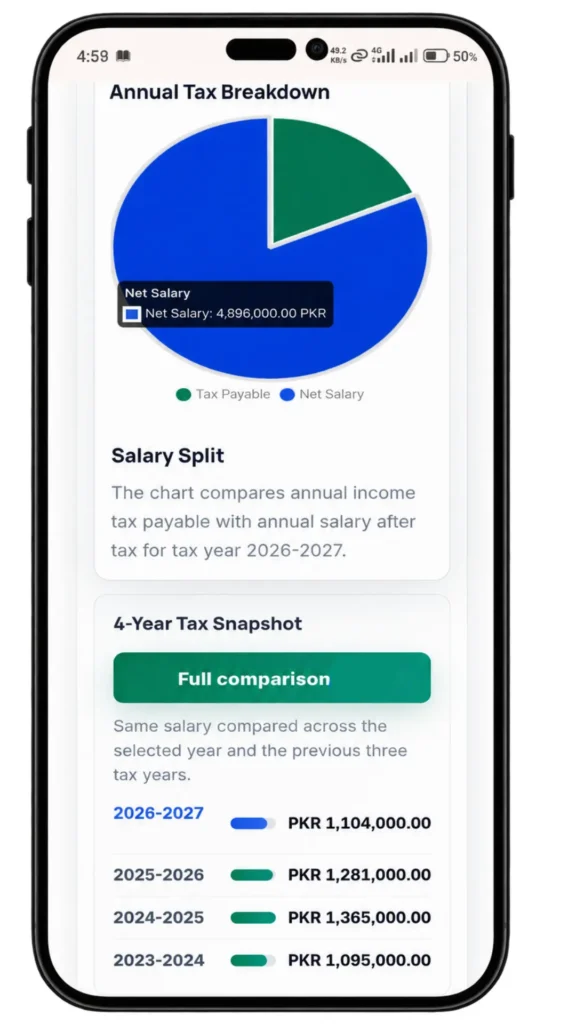
4-Year Tax Snapshot
Same salary compared across the selected year and the previous three tax years.
Calculate to see a quick year comparison.
Tax Slab Explanation
Enter income to see the applicable slab.
Your marginal tax explanation will appear here after calculation.
Take-Home Salary Insight
Your estimated monthly take-home salary will appear here.
Monthly Budget Impact
Your monthly tax deduction will appear here.
Tax Difference Insight
Previous year comparison will appear after calculation.
Tax Burden Meter
Effective tax rate means total annual tax divided by annual taxable income.
--
Tax burden not calculated
Your effective tax rate will appear here after calculation.
Progressive Tax Breakdown
Shows how tax is calculated across each slab your income passes through.
Calculate to see slab-by-slab tax allocation.
Tax Slab Highlight Table
The highlighted row shows the slab used for the current annual taxable income.
| Income range | Base tax | Marginal rate | Formula summary |
|---|---|---|---|
| Enter income and click Calculate to highlight the applicable slab. | |||
Among the last 4 available years for this income.
Best net salary year in this comparison window.
Change from the earliest compared year to your selected year.
Calculate to see visual year cards.
Tax & Take-Home Comparison Chart
Grouped bars for annual tax payable and net salary across four consecutive tax years.
Slab Position Across Compared Years
See whether your income falls in the same tax bracket across years or shifts between slabs.
Calculate to compare slab positions.
Detailed Year Comparison Table
Side-by-side figures for the selected tax year and the three previous years. Green differences mean you pay less tax; red means you pay more.
| Tax year | Annual tax | Tax visual | Monthly tax | Monthly after tax | Effective rate | vs Selected year |
|---|---|---|---|---|---|---|
| Enter income to compare tax across the selected year and previous three years. | ||||||
Salary Planning Tools
Optional estimates use the same selected tax year and income frequency.
Salary Raise Impact
Target Take-Home Salary
Salary Negotiation Insight
After calculating, see how much extra gross salary you would need in the selected year to match last year's take-home.
Tax Saving Notes
Actual tax may vary based on rebates, deductions, tax credits, exemptions, employer adjustments, or official FBR treatment. This calculator is for general salary planning only and is not legal advice.
Income Tax Calculator Pakistan 2026-27 | Salary Tax Calculator
Use our income tax calculator Pakistan tool to estimate salary tax for FY2026-27, Tax Year 2027. Enter your taxable monthly or annual salary to see your estimated annual income tax, monthly tax deduction, salary after income tax, effective tax rate and applicable tax slab.
Pakistan’s normal tax year runs for 12 months ending on June 30. This means income earned from July 1, 2026 to June 30, 2027 falls in Tax Year 2027. FBR’s current withholding-tax rate card for Tax Year 2027 is updated through the Finance Act 2026.
This calculator is designed primarily for salaried individuals. Under the Income Tax Ordinance, the special salaried-person tax rates apply where income chargeable under the head “Salary” exceeds 75% of the individual’s taxable income. If most of your taxable income comes from business, freelancing or another source, the salary calculator may not be the correct tool for your full tax liability.
How to use the salary tax calculator
Enter Your Income
Enter your taxable salary or income
Choose
select monthly or annual income.
Choose
Select FY2026-27 for current Tax Year 2027 calculations.
Tap “Calculate”
Review your annual tax, estimated monthly tax and salary after income tax.
View Results
Check the applicable slab, marginal rate and effective tax rate for a clearer explanation of the result.
A calculator result is an estimate, not an FBR assessment. Exemptions, tax credits, bonuses, salary changes, mixed sources of income and employer payroll adjustments can affect the final amount. Section 149 specifically requires employers to estimate salary income for the tax year and allows relevant adjustments to withholding during the year.
Pakistan salary tax slabs for FY2026-27 and Tax Year 2027
The following salary tax rates are based on the current FBR-published Income Tax Ordinance for Tax Year 2027.
Pakistan Government Finalize Tax Slabs Year 2026-27 These income tax slabs and rates will be applicable for the salary individuals. This income tax calculator also functions as per the following income tax slabs.
Annual taxable income | Equivalent monthly taxable salary if constant | Tax calculation |
|---|---|---|
Up to Rs. 600,000 | Up to Rs. 50,000 | 0% |
Rs. 600,001 to Rs. 1,200,000 | Over Rs. 50,000 to Rs. 100,000 | 1% of the amount above Rs. 600,000 |
Rs. 1,200,001 to Rs. 2,200,000 | Over Rs. 100,000 to about Rs. 183,333 | Rs. 6,000 + 11% of the amount above Rs. 1,200,000 |
Rs. 2,200,001 to Rs. 3,200,000 | Over about Rs. 183,333 to Rs. 266,667 | Rs. 116,000 + 20% of the amount above Rs. 2,200,000 |
Rs. 3,200,001 to Rs. 4,100,000 | Over about Rs. 266,667 to Rs. 341,667 | Rs. 316,000 + 25% of the amount above Rs. 3,200,000 |
Rs. 4,100,001 to Rs. 5,600,000 | Over about Rs. 341,667 to Rs. 466,667 | Rs. 541,000 + 29% of the amount above Rs. 4,100,000 |
Rs. 5,600,001 to Rs. 7,000,000 | Over about Rs. 466,667 to Rs. 583,333 | Rs. 976,000 + 32% of the amount above Rs. 5,600,000 |
Above Rs. 7,000,000 | Above about Rs. 583,333 | Rs. 1,424,000 + 35% of the amount above Rs. 7,000,000 |
The monthly figures in the second column are only convenient equivalents obtained by dividing the annual threshold by 12. A bonus, salary increase, job change or other taxable employment payment can change your annual salary even when your regular monthly basic salary stays the same.
How progressive tax slabs work
Pakistan’s salary tax table is progressive. Moving into a higher slab does not mean the new percentage is charged on your entire salary.
For example, an annual taxable salary of Rs. 3 million falls in the Rs. 2.2 million to Rs. 3.2 million bracket. The tax is not 20% of Rs. 3 million. Instead, the formula is:
Rs. 116,000 + 20% of the amount above Rs. 2,200,000
The amount above Rs. 2.2 million is Rs. 800,000, so:
Rs. 116,000 + (Rs. 800,000 × 20%) = Rs. 276,000
This distinction is why the marginal tax rate and effective tax rate are different.
Your marginal rate is the rate applying to additional taxable income within your current bracket. Your effective rate is total income tax divided by total taxable income.
What changed for FY2026-27?
FBR describes the 2026-27 changes as a reduction in tax rates for salaried individuals through a restructuring of the slabs. Additional intermediate brackets were added, and the income level at which the maximum 35% marginal rate begins increased from Rs. 4.1 million to Rs. 7 million.
There is another important change for higher-paid employees. Section 4AB currently provides a 10% surcharge in specified circumstances for individuals and associations of persons whose taxable income exceeds Rs. 10 million, but it expressly provides that no surcharge is payable in the case of an individual deriving income chargeable under the head Salary. The previous salary surcharge treatment should therefore not be added to a Tax Year 2027 salary calculation.
How salary income tax is calculated in Pakistan
A basic salary tax calculation starts with your taxable annual salary, not simply the number printed as “basic salary” on your employment contract.
The Income Tax Ordinance defines salary broadly. It includes pay and wages as well as items such as overtime, bonus, commission, fees, certain allowances, perquisites and other employment-related amounts, subject to the exemptions and special rules in the Ordinance.
For a regular monthly taxable salary, a simple estimate works like this:
Annual taxable salary = monthly taxable salary × 12
Next, identify the annual tax slab. Use the fixed or base amount shown in that slab and add the stated percentage of income above its threshold.
For example, for Rs. 150,000 taxable salary per month:
Rs. 150,000 × 12 = Rs. 1,800,000 annual taxable salary
The applicable formula is:
Rs. 6,000 + 11% of the amount above Rs. 1,200,000
Therefore:
Rs. 1,800,000 – Rs. 1,200,000 = Rs. 600,000
Rs. 600,000 × 11% = Rs. 66,000
Rs. 66,000 + Rs. 6,000 = Rs. 72,000 annual tax
A simple monthly estimate is:
Rs. 72,000 ÷ 12 = Rs. 6,000 per month
Estimated monthly salary after income tax is therefore:
Rs. 150,000 – Rs. 6,000 = Rs. 144,000
Salary tax examples and estimated take-home pay
The following examples assume a constant taxable salary for all 12 months, no additional taxable bonus and no separate exemption, credit or other adjustment. They use the Tax Year 2027 salary slabs published in the current FBR Income Tax Ordinance.
Taxable salary per month | Annual taxable salary | Estimated annual income tax | Simple monthly tax estimate | Salary after income tax per month |
|---|---|---|---|---|
Rs. 50,000 | Rs. 600,000 | 0 | Rs. 0 | Rs. 50,000 |
Rs. 75,000 | Rs. 900,000 | Rs. 3,000 | Rs. 250 | Rs. 74,750 |
Rs. 100,000 | Rs. 1,200,000 | Rs. 6,000 | Rs. 500 | Rs. 99,500 |
Rs. 150,000 | Rs. 1,800,000 | Rs. 72,000 | Rs. 6000 | Rs. 144,000 |
Rs. 200,000 | Rs. 2,400,000 | Rs. 156,000 | Rs. 13,000 | Rs. 187,000 |
Rs. 250,000 | Rs. 3,000,000 | Rs. 276,000 | Rs. 23,000 | Rs. 227,000 |
Rs. 300,000 | Rs. 3,600,000 | Rs. 416,000 | Rs. 34,667 | about Rs. 265,333 |
Rs. 400,000 | Rs. 4,800,000 | Rs. 744,000 | Rs. 62,000 | Rs. 338,000 |
Rs. 500,000 | Rs. 6,000,000 | Rs. 1,104,000 | Rs. 92,000 | Rs. 408,000 |
Rs. 750,000 | Rs. 9,000,000 | Rs. 2,124,000 | Rs. 177,000 | Rs. 573,000 |
Rs. 1,000,000 | Rs. 12,000,000 | Rs. 3,174,000 | Rs. 264,500 | Rs. 735,500 |
Example: tax on Rs. 100,000 monthly salary
A taxable monthly salary of Rs. 100,000 produces annual taxable salary of Rs. 1.2 million.
The rate for income above Rs. 600,000 and up to Rs. 1.2 million is 1% of the excess over Rs. 600,000.
Rs. 1,200,000 – Rs. 600,000 = Rs. 600,000
1% × Rs. 600,000 = Rs. 6,000 annual tax
The simple monthly estimate is:
Rs. 6,000 ÷ 12 = Rs. 500
So estimated salary after income tax is approximately Rs. 99,500 per month.
Example: tax on Rs. 250,000 monthly salary
Annual taxable salary:
Rs. 250,000 × 12 = Rs. 3,000,000
Applicable Tax Year 2027 formula:
Rs. 116,000 + 20% of amount above Rs. 2,200,000
Amount above threshold:
Rs. 3,000,000 – Rs. 2,200,000 = Rs. 800,000
Tax on that excess:
Rs. 800,000 × 20% = Rs. 160,000
Annual tax:
Rs. 116,000 + Rs. 160,000 = Rs. 276,000
Simple monthly tax estimate:
Rs. 276,000 ÷ 12 = Rs. 23,000
Estimated monthly salary after income tax:
Rs. 250,000 – Rs. 23,000 = Rs. 227,000
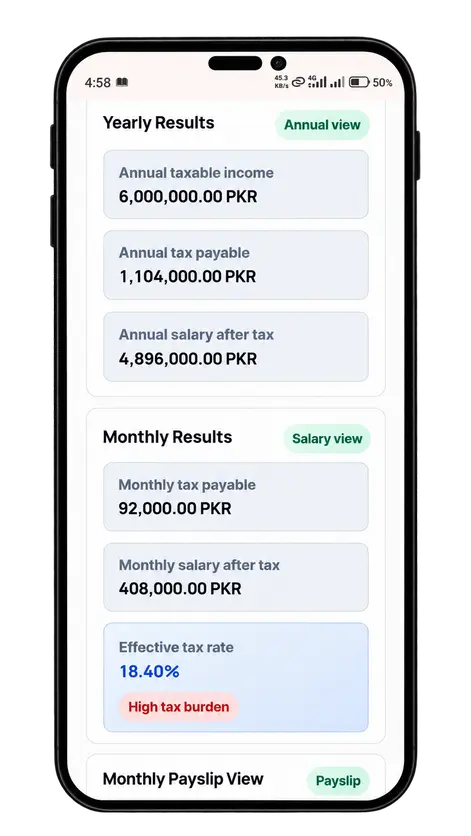
Example: tax on Rs. 500,000 monthly salary
Annual taxable salary:
Rs. 500,000 × 12 = Rs. 6,000,000
The applicable formula is Rs. 976,000 plus 32% of taxable income above Rs. 5.6 million.
Rs. 6,000,000 – Rs. 5,600,000 = Rs. 400,000
Rs. 400,000 × 32% = Rs. 128,000
Rs. 976,000 + Rs. 128,000 = Rs. 1,104,000 annual tax
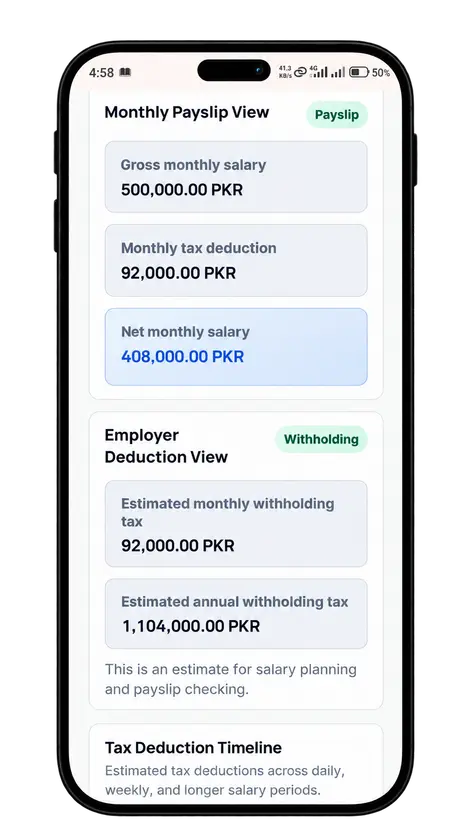
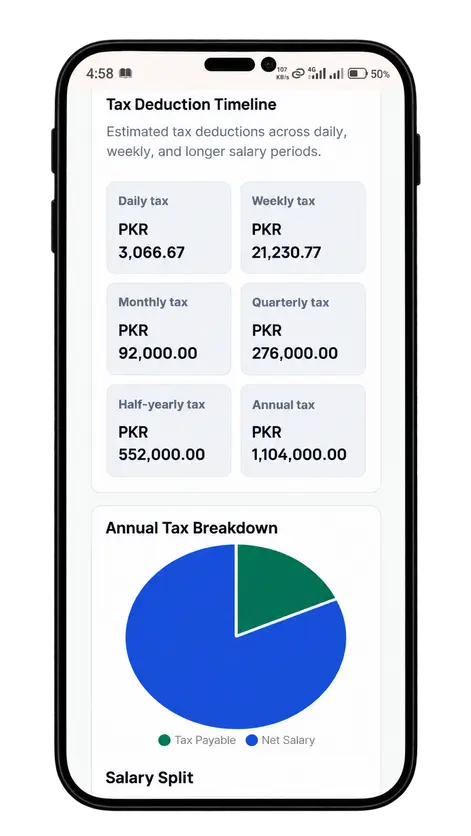
That gives a simple monthly estimate of Rs. 92,000 and salary after income tax of approximately Rs. 408,000 per month.